The largest crypto hack on record: Binance puts its losses at about $6.3 billion, and the FBI points to North Korea.
Binance estimates about $6.3 billion in losses and the FBI attributes the theft to North Korea. Plus: the 20-indicator market table, the Fed holding at 3.75–4.00% on a 10–2 vote, four scenarios to Q3 2027 with weights K1 15 · K2 45 · K3 25 · K4 15, and the HYPE token profile with its price history since launch.
00 — Editor's Letter
Over $6 billion. Binance estimates its losses at about $6.3 billion, and the FBI says North Korea is responsible for the theft of more than $6 billion in virtual assets. On Binance's own figure, this is the largest theft in recorded crypto history, more than four times the Bybit hack of February 2025.
Risk assets weakened over the past two weeks. Over the 15-session window (30/10 against 09/10; gold, silver and oil as of 29/10) silver fell 18.8%, the Kospi fell 13.5%, the Nikkei fell 8.3% and gold fell 7.5%, while Brent crude rose 8.3%. On 28/10 the Fed held its rate range at 3.75–4.00% on a 10–2 vote, with two members wanting a 25-basis-point increase. The 10-year US Treasury yield on 29/10 was 4.98%. Bitcoin's 31/10 daily candle closed at $77,582, down 4.94% from the 16/10 candle; over the whole of October Bitcoin fell 7.2%, Ethereum 16.0% and Solana 19.1%.
On the news side: Strive bought another 6,182 bitcoin, the OCC approved the formation of Ripple National Trust Bank, J.P. Morgan put JPM Coin on Ethereum, and Trezor warned customers who bought devices from CryptoBilis. This issue's token profile is HYPE.
A note on timing: the figures are cut at the end of 31/10/2026 UTC, which is 07:00 on 01/11 in Vietnam. Equity indices are as of 30/10; gold, silver, Brent and Treasury yields are as of 29/10; FRED's broad dollar index is as of 23/10. Anything taken later than the cut-off is marked separately where it appears.
01 — Global Equities and Macro
The 20-Indicator Table
- S&P 500 — 7,580 · −2.96%
- Euro Stoxx 50 — 6,131 · −0.68%
- FTSE 100 — 10,730 · +1.68%
- Nikkei 225 — 63,290 · −8.32%
- Hang Seng — 23,294 · −3.79%
- Shanghai — 3,599 · −5.63%
- Kospi — 5,731 · −13.51%
- Taiwan — 45,212 · −8.32%
- Singapore — 5,377 · −0.47%
- India · Nifty 50 — 23,053 · +2.37%
- Australia · ASX 200 — 8,908 · +2.20%
- Vietnam · VN-Index — 1,741.62 · +0.38%
- Gold — $3,899 · −7.53%
- Silver — $49.28 · −18.78%
- Brent crude — $113.43 · +8.32%
- Dollar · broad index — 121.32 · −0.38%
- 10-year yield — 4.98% · −30 basis points
- VIX · fear — 19.42 · +30.86%
- USD/VND — 25,799 · −0.35%
- Crypto market cap · top 30 — $2.53 trillion · −4.55%
Against the level 15 sessions earlier (09/10/2026); close of 30/10/2026. Where an index was closed on 09/10, the nearest earlier session is used (Taiwan: 08/10). Separate reference points: gold, silver and Brent are as of 29/10 (the futures series ended that day); the broad dollar index is as of 23/10 against 01/10 (FRED publishes late; 15 observations); the 10-year yield is as of 29/10 against 07/10, with the change in basis points; the crypto market cap is the sum of the market caps of the 30 largest coins (about 97% of the whole market), closing value on 31/10 against 16/10. Sources: Yahoo Finance, VNDirect, FRED, CoinGecko.
14 red cells, 6 green. The green cells are the FTSE 100, India's Nifty 50, Australia's ASX 200, the VN-Index, Brent crude and the VIX. Among the indices and commodities, the sharpest fall is silver (−18.78%) and the sharpest rise is Brent crude (+8.32%).
Fed
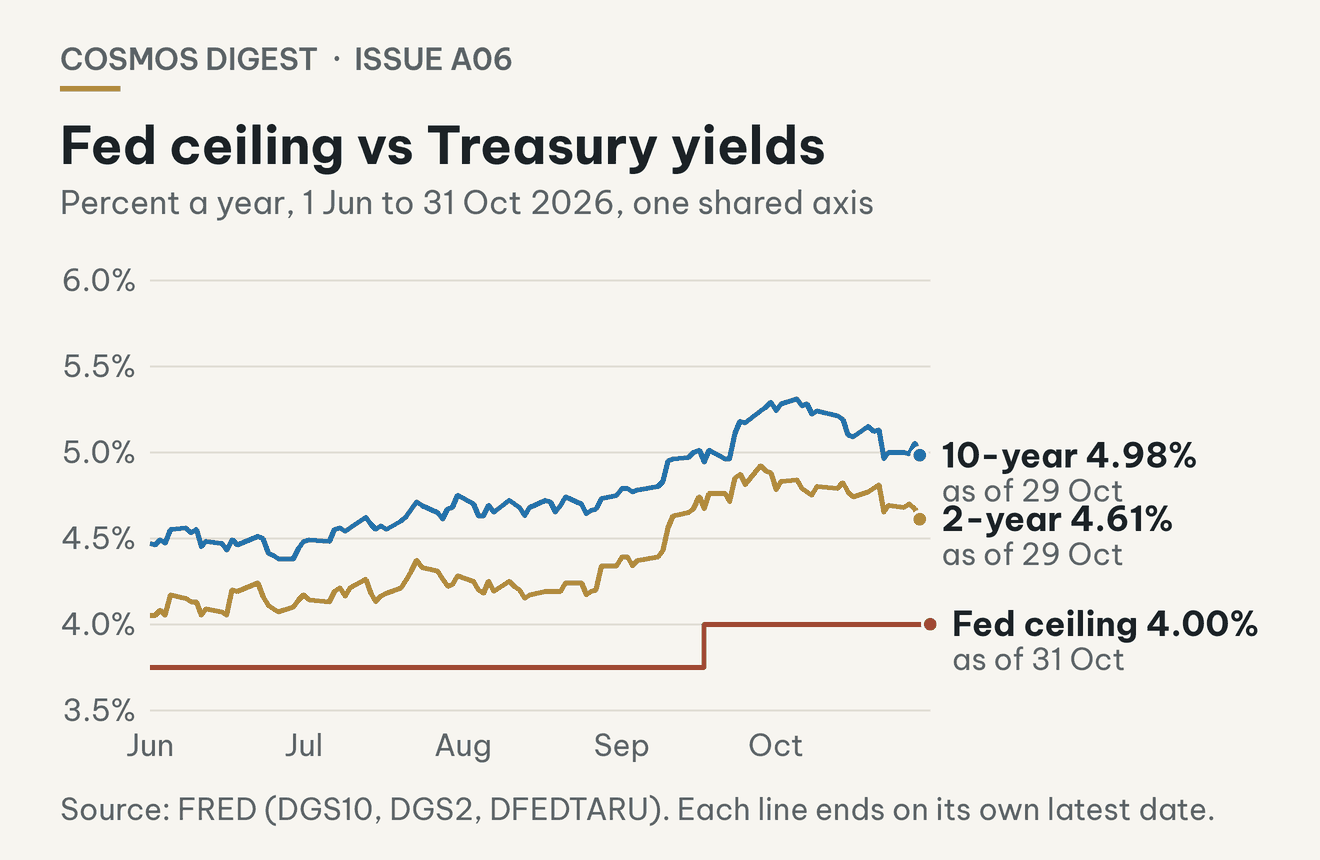
On 28/10 the Federal Open Market Committee held the federal funds target range at 3.75–4.00% on a 10–2 vote; Lisa Cook and Beth Hammack wanted a 25-basis-point increase. The statement said inflation remains elevated and did not mention the December meeting. The ceiling is 4.00% (31/10) and the effective rate is 3.88% (29/10). The 2-year yield is 4.61% (29/10), 61 basis points above the ceiling. The 10-year yield is 4.98% (29/10); it was 5.05% on the meeting day, 28/10, and the October peak was 5.31% on 05/10. · Fed, 28/10/2026 · FRED
Global Equities
The S&P 500 is at 7,580.07 points (−2.96%). In Europe the Euro Stoxx 50 is −0.68% and the FTSE 100 +1.68%, one of four indices that rose.
Asia
Sharp falls: Kospi −13.51%, Taiwan −8.32%, Nikkei −8.32%, Shanghai −5.63%, Hang Seng −3.79%, Singapore −0.47%. Rises: Nifty 50 +2.37%, ASX 200 +2.20%.
Vietnam
The VN-Index is at 1,741.62 points on 30/10, +0.38% against 09/10. USD/VND is 25,799 (−0.35%).
Dollar, Gold, Silver, Oil
The broad dollar index is 121.32 on 23/10, −0.38% against 01/10. Gold is $3,898.9 an ounce (−7.53%), silver $49.28 an ounce (−18.78%) and Brent $113.43 (+8.32%) on 29/10. Gold, silver and oil prices are futures. The VIX is 19.42 (+30.86%).
The Bridge to Crypto
Bitcoin's 31/10 candle closed at $77,582, −4.94% against the 16/10 candle. The Fear and Greed Index is 30 (Fear), down from 63 on 16/10.
02 — World Finance
The Fed held rates but two members voted to raise them. PCE inflation for September was still 3.6% year on year, and the US economy grew at an annualised 3.4% in the third quarter.
Interest-Rate Box
- Fed ceiling — 4.00% · 31/10 · unchanged against 16/10
- 2-year yield — 4.61% · 29/10 · −16 basis points against 07/10
- 10-year yield — 4.98% · 29/10 · −30 basis points against 07/10
- 30-year yield — 5.32% · 29/10 · −35 basis points against 07/10
- 10-year minus 2-year spread — 0.37 points · 29/10
- Dollar · broad index — 121.32 · 23/10 · −0.38% against 01/10
Each indicator has its own cut-off date; changes are against the 15 observations before. Source: FRED.
On CPI: there is no new CPI reading this period; October CPI is published on 10/11 (BLS). The latest reading is September CPI, published on 14/10 and covered in A05.
Macro Indicators
- Effective Fed rate · ceiling — 3.88% · 4.00% · 29/10 · 31/10
- Fed balance sheet — $6.75 trillion (−$8.0 billion against the previous week) · 28/10
- Reverse repo — $4.375 billion · 30/10
- Treasury General Account (TGA) — $999.7 billion (+$47.7 billion against the previous week) · 28/10
- M2 money supply — $23.41 trillion · September 2026
- High-yield bond spread — 3.26% (October peak 3.40% on 22/10) · 29/10
- Brent crude · gold — $113.43 · $3,898.9 an ounce · 29/10
US GDP, Q3 · Preliminary Estimate
The BEA published on 29/10: real GDP grew at an annualised 3.4% in the third quarter (0.8% on the quarter), against 2.2% in the second quarter. Real final sales to private domestic purchasers grew 4.9%, against 4.6% in the second quarter. The quarterly PCE price index rose 2.1% at an annual rate and the core index 2.5% (second quarter: 5.0% and 3.3%); these are annualised rates for the whole quarter, not changes against the same month a year earlier. The second estimate is expected on 25/11. · BEA, 29/10/2026
September PCE
Also on 29/10: personal income in September rose $54.5 billion (0.2%), disposable income rose $52.7 billion (0.2%) and consumer spending rose $113.1 billion (0.5%); the saving rate was 3.8%. The PCE price index rose 0.5% in the month and the core index 0.3%. Against the same month a year earlier, the PCE price index rose 3.6% and the core index 3.1%. The October release is expected on 25/11. · BEA, 29/10/2026
ECB Holds All Three Rates
On 29/10 the ECB held the deposit facility, main refinancing and marginal lending rates at 2.50%, 2.65% and 2.90%. The statement said energy prices continue to rise, creating upside risks to inflation and downside risks to growth; underlying inflation has been broadly stable; and financial conditions have tightened since the previous meeting. The APP and PEPP portfolios continue to decline as maturing principal is not reinvested. · ECB, 29/10/2026
Eurostat · Q3 GDP, Flash Estimate
On 30/10 Eurostat estimated that eurozone GDP grew 0.4% in the third quarter against the previous quarter, and EU GDP 0.5%; France is one of the countries with a contraction. This is a flash estimate, based on incomplete data and subject to revision; the next release is on 13/11. · Eurostat, 30/10/2026 · Xinhua
03 — Crypto Market Overview
Prices and 15-session changes: the UTC daily candle of 31/10 against the 16/10 candle, Binance. Sources: Binance, Alternative.me, CoinGecko.
- Bitcoin — $77,582 · −4.94% over 15 sessions
- Ethereum — $2,256 · −6.93% over 15 sessions
- Solana — $95.54 · −8.53% over 15 sessions
- BNB — $703.95 · −2.44% over 15 sessions
- Fear and Greed — 30 · Fear (16/10: 63 · Greed)
- October — Bitcoin −7.2% · ETH −16.0% · SOL −19.1%
Bitcoin · 15 Sessions and 12 Months
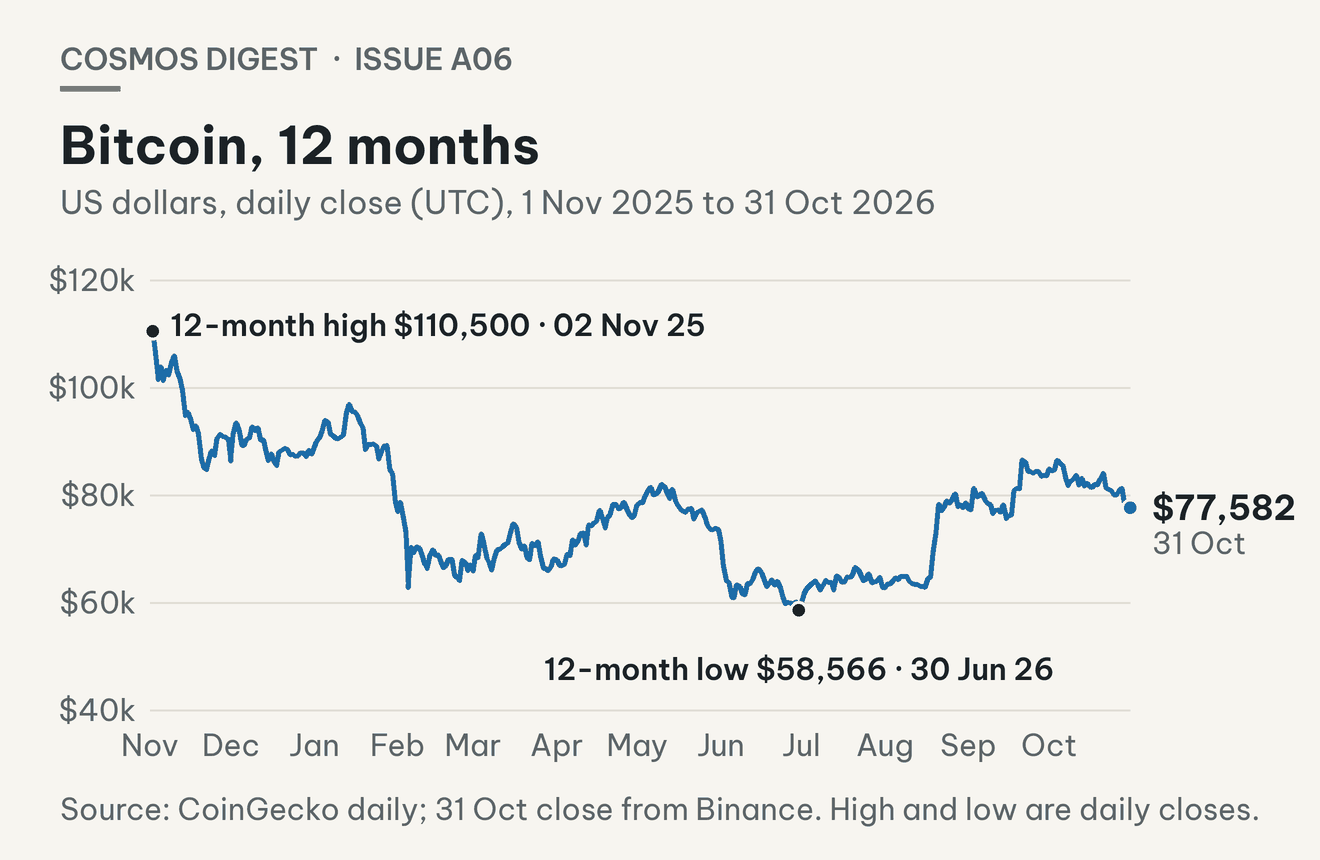
The 31/10 candle closed at $77,582, −4.94% against $81,616 on 16/10. The low since 16/10 is $76,326 (30/10). Over 12 months the high is $110,500 (candle close of 02/11/2025) and the low is $58,566 (candle close of 30/06/2026). Bitcoin is 29.8% below the high and 32.5% above the low.
October opened at $83,624 and closed at $77,582 (−7.2%); the monthly high was $87,220 on 02/10, followed by three weekly closes, each lower than the one before: $83,773 → $82,116 → $80,154 (weeks ending 11/10, 18/10 and 25/10). Ethereum fell 16.0% in the month and Solana 19.1%: both were weaker than Bitcoin.
Derivatives · Funding
- BTCUSDT — funding 0.0100% (16:00 UTC period) · open interest 96,320 BTC on 31/10 · value $7.45 billion
- ETHUSDT — funding −0.0036% · open interest 2,336,915 ETH · value $5.24 billion
- SOLUSDT — funding 0.0070% · open interest 8,835,091 SOL · value $0.85 billion
Positive funding means leveraged buyers pay sellers, every 8 hours. Values are Binance's own figures (openInterestHist). Source: Binance fundingRate and openInterestHist, historical data to the end of 31/10.
Top Gainers and Losers, 14 Days
Top gainers, 14 days:
- KNTQ Kinetiq #183 — +93.7%
- BEAM Beam #147 — +82.9%
- PEPE Pepe #46 — +26.8%
- EDGE edgeX #233 — +22.4%
- HYPE Hyperliquid #10 — +14.2%
- ZEC Zcash #11 — +13.5%
- M MemeCore #50 — +11.0%
- LIT Lighter #82 — +10.7%
- HASH Provenance Blockchain #115 — +9.6%
- NIGHT Midnight #88 — +9.4%
Top losers, 14 days:
- Q Quack AI #219 — −76.1%
- AKE Akedo #165 — −69.7%
- BTW Bitway #55 — −50.4%
- ZK ZKsync #247 — −29.5%
- RAIN Rain #22 — −29.0%
- STRK Starknet #127 — −28.6%
- S Sonic #201 — −24.3%
- TIA Celestia #113 — −23.6%
- PEARL Pearl #99 — −22.8%
- SAND The Sandbox #221 — −21.1%
Among the 250 largest coins by market cap, with stablecoins, wrapped tokens and pegged assets removed. Some tickers have market caps reported by the projects themselves. Source: CoinGecko, taken at 18:09 UTC on 01/11: CoinGecko does not allow look-back by date, so this table is about 18 hours later than the 31/10 cut-off.
Market Breadth
Of the 220 remaining coins whose price changed over 14 days, 62 rose and 158 fell: 28% of coins rose. Same CoinGecko reading as the table above.
04 — Crypto Moves
Strive · Another 6,182 Bitcoin
Form 8-K of 26/10: between 17/10 and 23/10 Strive bought 6,182 bitcoin at an average of about $82,732 per bitcoin, including fees and expenses. On 23/10 the company held 43,000 bitcoin, up from 36,818 on 16/10. Cash and cash equivalents were $504.4 million, up from $317.5 million. Its STRC holding remains 505,000 shares. · SEC, 26/10/2026
Ripple · OCC Approves National Trust Bank
On 26/10 Ripple said the OCC had given final approval to establish Ripple National Trust Bank, after the conditional approval of December 2025. The stated scope: managing the segregated reserve behind RLUSD, acting as trustee of collateral for RLUSD holders, and custody of digital assets in trust once it opens. RLUSD is still issued by Standard Custody & Trust Company. Ripple puts RLUSD's market cap at $2.5 billion; BNY is the main custodian of the reserve. · Ripple, 26/10/2026
J.P. Morgan · JPM Coin on Ethereum
On 19/10 Kinexys by J.P. Morgan put JPM Coin (ticker JPMD), a dollar-denominated deposit token, on Ethereum for institutional clients. The token already ran on Base. Kinexys cites more than $4 trillion in cumulative volume and about $7 billion a day on average; this is for the whole platform, not JPM Coin alone. · J.P. Morgan, 19/10/2026
FINMA · First Retail Bitcoin Fund
On 20/10 FINMA approved Switzerland's first listed fund investing directly in Bitcoin, a fund for alternative investments under Swiss law, with its own risks. FINMA allowed an exemption from the risk-spreading rule, on the grounds that Bitcoin has a long trading history and high volume compared with other cryptocurrencies. Other issuers have filed or said they will file. FINMA stressed that money put into Bitcoin, including through an approved fund, can still lose significant value. · FINMA, 20/10/2026
ENS · Version 2 on Mainnet
On 27/10 ENS said ENSv2 is live on Ethereum mainnet. Existing names keep working and do not need to be re-registered; upgrading to the new version is optional and is done in the ENS app. · ENS, 27/10/2026
Ethereum · Glamsterdam Delayed on Hoodi
On 22/10 the Ethereum Foundation said the Glamsterdam upgrade on the Hoodi test network, previously scheduled for 26/10, has been delayed; there is no replacement date yet. The delay does not set a date for mainnet, and ETH holders on mainnet need to do nothing because of this announcement. · Ethereum Foundation, 22/10/2026
Trezor · Warning for CryptoBilis Customers
On 30/10 Trezor posted that on 28/10 it received a responsible-disclosure report about a Safe 5 bought from CryptoBilis in August through Tokopedia, claiming that an unfamiliar component had been implanted in the device. Trezor has not yet received the device to examine and treats the report as credible. CryptoBilis was an official retail partner of Trezor in Southeast Asia and was removed on 09/10. Customers who bought a Trezor from CryptoBilis since March 2026 are advised to move their assets to a new wallet with a new recovery phrase, not to activate unused devices, and not to load old backups onto such a device. No customer has reported a loss. Customers in this group are offered a replacement device shipped directly, or a voucher. · Trezor, 30/10/2026
Binance · Security Incident
Binance says the loss is about $6.3 billion, of which about $3 billion has been frozen; withdrawals are paused while deposits still work. Details are in section 07.
05 — Market Outlook
The FOMC switch has been flipped to the second branch: two votes for a rise, but the 10-year yield fell below 5%. Fable, Chief Strategy Officer, raises K2 from 40 to 45 and cuts K1 from 20 to 15; K3 and K4 are unchanged.
Figures are cut at the end of 31/10/2026 (UTC); figures taken after the cut-off carry their own time stamps.
The Three Answers A05 Promised
The FOMC switch (28/10) has flipped. The Fed held the range at 3.75–4.00% on a 10–2 vote; Cook and Hammack wanted a 25-basis-point rise. The statement upgraded its description of the economy from "solid" to "expanding at a strong pace", kept "inflation remains elevated", and did not mention the December meeting; the policy sentence says "the accumulation of more information will help the Committee determine the policy stance appropriate", which is exactly the "watch more data" wording. · FOMC statement, 28/10/2026
Did core PCE for September fall below 3.0%? Not yet. The core PCE price index rose 3.12% year on year in September (the BEA rounds to 3.1%; +0.32% in the month) and the headline 3.65% (BEA 3.6%; +0.49% in the month), calculated from FRED's PCEPILFE and PCEPI series, published by the BEA on 29/10. After three prints hovering around 3.0%, core edged up instead of down. · FRED PCEPILFE
Did the 10-year yield hold above 5.0% through 28/10? No: it closed at 5.05% on 28/10 and fell to 4.98% on 29/10; the October peak is 5.31% on 05/10. The 2-year yield is 4.61% on 29/10, 61 points above the Fed ceiling (A05: 82 points). Worth noting: the 10-year yield is down 30 basis points against 07/10 (15 observations) even though two Fed members called for a rise; there is not enough evidence to attribute the fall to any single event. · FRED DGS10 · FRED DGS2
Did the high-yield spread rise above 4.0%? Not yet: 3.26% on 29/10, with the October peak at 3.40% on 22/10 (A05: 3.25%). The K4 fuse warmed up and cooled; it has not blown. · FRED BAMLH0A0HYM2
Bitcoin against $83,000 and $86,597. The 31/10 candle closed at $77,582 (Binance), −4.94% against the 16/10 candle; the low since 16/10 is $76,326 on 30/10. Three consecutive weekly closes lower: $83,773 → $82,116 → $80,154 (week ending 25/10). October candle: open $83,624, close $77,582, −7.2%. Ethereum −16.0% in the month ($2,686 → $2,256), Solana −19.1% ($118.1 → $95.5). Fear and Greed 30 on 31/10, from 63 on 16/10.
Choosing the Switch Branch
Two votes for a rise sit between the first two branches of A05's switch table: the wording of the statement is branch one ("watch more data"), while the votes are branch two. A05 defined branch two by the condition "there are votes for a rise, or the statement stresses inflation"; the votes condition has occurred, so this issue applies the branch it promised: K1 15 · K2 45 · K3 25 · K4 15. The rates market reads it the same way: right after the press conference FedWatch priced 83–85% for a 25-basis-point Fed rise on 09/12 (Kiplinger, 28/10); by 31/10 the OIS contracts were down to 73% (rateprobability.com, 31/10). Two numbers run against branch two, the 10-year yield at 4.98% and the high-yield spread at 3.26%, and they will decide whether A07 cuts K3.
Four Scenarios · From $77,582 · To Q3 2027
K1 · Late Soft Landing — weight 15 (from 20). The Fed stops at 4.00%, core PCE turns down in Q4, and the 10-year yield falls below 4.5% in Q1 2027. Bitcoin regains $83,000 and closes a week above $86,597. Cut by the switch: two votes for a rise and core PCE at 3.12% (edging up) close the door on "the Fed is done" in Q4.
K2 · Higher for Longer, the base case — weight 45 (from 40). The Fed raises at most once more (December), then stays at 4.00–4.25% until mid-2027; the 10-year yield is stuck at 4.8–5.3%. Bitcoin ranges between $62,000 and $86,000, bounced off the ceiling band; ETFs reverse with the news; altcoins are weaker than Bitcoin (October: ETH −16%, SOL −19% against BTC −7%). Raised by the switch; October already played out as K2: the Fed stood still, prices cooled on their own, nothing broke.
K3 · Second Wave — weight 25 (held). Oil and producer prices push headline inflation above 4%; the Fed raises in December and signals more; the 10-year yield returns above 5.2% throughout Q1 2027. Bitcoin loses the $62,000 floor and tests $52,000–58,000. The switch holds 25; but the 10-year yield has fallen below 5% and the high-yield spread has dropped to 3.26%, so this branch has lost one of its two pillars. A07 cuts K3 if the 10-year yield is still below 5.0% on 13/11.
K4 · A Break from Leverage or a Counterparty — weight 15 (held). A credit link or a large exchange fails to pay; the Fed cuts in an emergency; Bitcoin falls about 30% and then recovers in a V. The Binance incident of 29/10 is a K4 test outside the script: the exchange has declared it will cover all losses from the SAFU fund and company funds (section 07), and the high-yield spread of 3.26% has not reacted. K4 changes weight if that spread rises above 4.0% or if Binance does not reopen withdrawals on all the main networks.
What the Market Is Pricing
- Fed rise of 25 points on 09/12? 83–85% (CME FedWatch, right after the 28/10 press conference) · 73% (OIS, 31/10). · Kiplinger · rateprobability.com
- What does the 2-year yield say? 4.61% = Fed ceiling of 4.00% + 61 points (A05: 82): a rise is still priced, but less than before. · FRED DGS2 · 29/10
- US Bitcoin ETFs in October: net outflow of $515.9 million over 22 sessions (13 inflow sessions, 9 outflow sessions); September net inflow $2.65 billion. The last three weeks of the month (12–30/10): −$129.6 million. · Farside · read at 18:20 UTC on 01/11, data to the 30/10 session
- ETFs after the FOMC: 29/10: +$17.2 million · 30/10: −$643.2 million (the largest outflow session of the month, the day after the Binance incident) · 31/10: a Saturday, no session. · Farside, as above
- FMR-10 (Cosmos Digital's ETF momentum indicator): +0.11 on 30/10 (neutral), from −0.83 on 16/10: the indicator has returned to neutral after the run of outflows and has not yet turned to net inflows; the 30/10 session alone was still a heavy outflow. · calculated from Farside data
- Bitcoin leverage: Binance funding of 0.0100% per 8 hours in all three periods on 31/10 (buyers pay); Binance perpetual open interest of 96,320 BTC on 31/10, up 1.6% against 28/10 (94,792) while the price fell 4.6%: leverage came in to buy the dip. · Binance Futures · historical API data, 31/10
- K4 fuse: high-yield spread 3.26% (29/10), monthly peak 3.40% (22/10). · FRED BAMLH0A0HYM2
The last three lines tell one story: institutional money (ETFs) left in exactly the session after the Binance incident, while retail money (perpetual contracts) added long positions as the price fell. This is a setup prone to one more leg down before the price stabilises; the confirmation condition is open interest falling while the price holds still.
Bitcoin Between Two Structural Bands
The two bands are unchanged: ceiling $83,000–86,000, floor $62,000–65,000. Bitcoin at $77,582 sits between them: it needs to rise about 7% to reach the lower edge of the ceiling band ($83,000) and fall about 16% to reach the upper edge of the floor band ($65,000); the monthly low has not touched either edge. October did the job of K2: the ceiling band pushed the price down (high of $87,220 on 02/10, then three weeks of declines), and the floor band has not been tested. The next ruling is still by weekly close: above $86,597 is K1; between the bands is K2; losing $62,000 is K3. The two bands are structural zones defined by Cosmos Digital, not price targets.
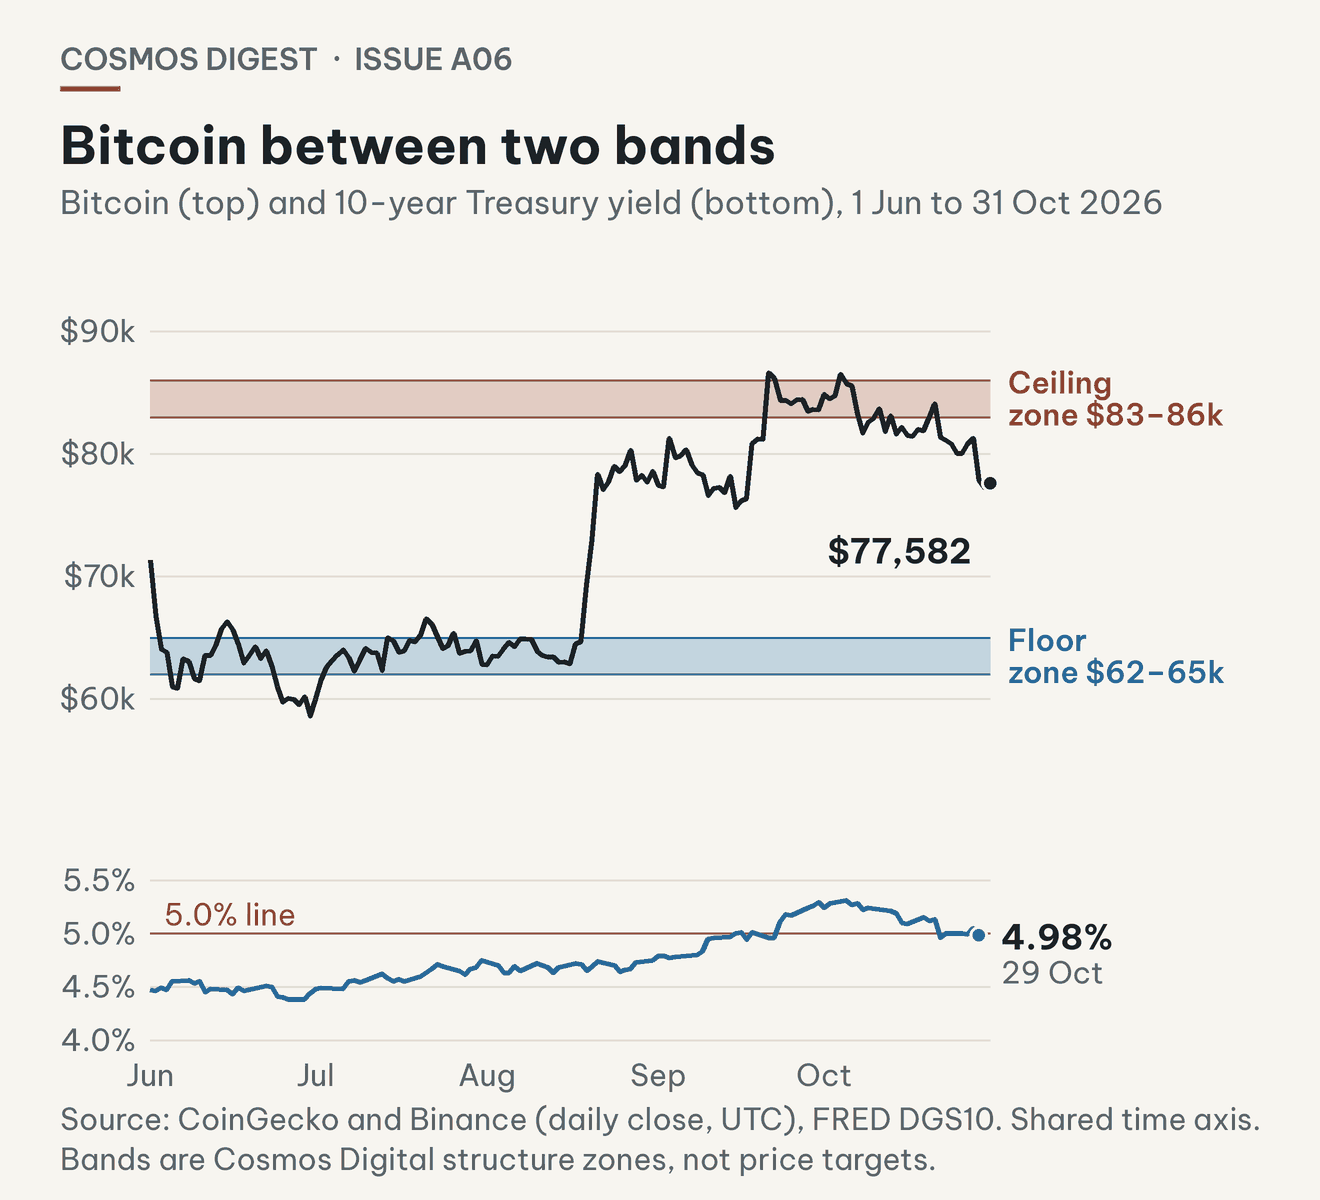
Upper panel: Bitcoin's closing price; lower panel: the 10-year yield, on the same time axis, each panel with its own scale. Sources: CoinGecko, Binance, FRED.
What We Will Watch and Report in A07 (16/11)
The October jobs report (BLS, 06/11): whether September's +29,000 is a trend or noise. October CPI (BLS, 10/11): whether core rises further above 2.6%. Whether the 10-year yield on 13/11 is above or below 5.0%, the threshold for cutting K3. The probability of a 09/12 rate rise on FedWatch. ETF flows in the first two weeks of November: whether FMR-10 rises above +0.5. The weekly closes of 08/11 and 15/11 against $76,326 and $83,000. Binance: the next round of withdrawal reopenings and the Proof of Reserves report; whether the hackers' wallet cluster starts swapping ETH into Bitcoin through THORChain (section 07). The second estimate of Q3 GDP and October PCE (both on 25/11) fall after A07, in A08.
— Fable, Chief Strategy Officer, Cosmos Digital
06 — One Token Per Issue
HYPE · ticker HYPE · the native token of Hyperliquid · ranked 10th by market cap.
HYPE is the native token of Hyperliquid, ranked 10th by market cap. It rose 9.6% over 15 sessions while Bitcoin fell 4.9%; the rise is tied to a news item specific to it, not to the market as a whole.
What It Is and How It Works
HYPE is the native token of Hyperliquid, a layer-1 blockchain running HyperBFT consensus, made up of HyperCore (a perp and spot order book running directly inside the protocol) and HyperEVM (an Ethereum-compatible smart-contract environment sharing one state with HyperCore). The token's jobs: staking to validators to secure the network; paying gas on HyperEVM; reducing trading fees by stake tier (from 5% when holding more than 10 HYPE to 40% when staking more than 500,000 HYPE); and being the target of the buyback mechanism. All trading fees go to the community (HLP, the Assistance Fund, market deployers), and the Assistance Fund automatically converts fees to HYPE during L1 execution and burns that HYPE, removing it from supply permanently. The Hyperliquid homepage states that 99% of protocol revenue goes into the Assistance Fund. · Hyperliquid docs, Fees · Hyperliquid
Origins
The Hyperliquid perp exchange ran for more than a year and was among the largest decentralised exchanges by volume before it had a token. The genesis event took place at 07:30 UTC on 29/11/2024, with a maximum supply of 1 billion: 31.0% (310 million) airdropped to eligible users, fully unlocked; 38.888% (388.88 million) for later distribution and community rewards; 23.8% to core contributors, locked for one year after genesis; 6.0% (60 million) the Hyper Foundation budget; 0.3% (3 million) community grants; and 0.012% (120,000) for HIP-2. The genesis post states "no allocation for private investors, centralised exchanges or market makers". · Hyper Foundation, 28/11/2024 · The Block, 28/11/2024
The one-year lock ended on 29/11/2025: the first distribution to the core group was about 1.75 million HYPE on 29/11/2025, the second 1.2 million on 06/01/2026; since then distributions "if any" fall on the 6th of each month; the development team says the vesting schedule is "non-linear" and is not published in full. In December 2025 the Hyper Foundation proposed burning about $1 billion of HYPE accumulated in the Assistance Fund. · The Block, 29/12/2025
Team and Backers
Hyperliquid Labs builds the protocol; the Hyper Foundation holds 6.0% of supply for operations and is the party that published the genesis. The Hyper Foundation site states "No investors. No paid market makers. No fees to any company." No separate funding round has been disclosed, so there are no backing funds to list. · Hyper Foundation
The Problem It Solves
An order book for perps placed directly in the protocol, at near-centralised-exchange speed: the Hyper Foundation publishes a block time of 0.07 seconds and a capacity of 200,000 transactions per second. Fees go not to a company but to liquidity providers and the burn mechanism. HIP-3 lets third parties deploy their own perp markets (stocks, indices, commodities, foreign exchange) on Hyperliquid's infrastructure and keep up to 50% of the fees of the market they open; this is the door US institutions are now walking through (see "What Is Coming"). · Hyper Foundation · Hyperliquid docs, Fees
Financials · Supply and Price
- Price — $88.08 · 31/10 candle close · Binance
- Market cap — $21.09 billion · ranked 10th · calculated from the closing price × circulating supply
- 24-hour volume — $1.05 billion · CoinGecko, 18:07 UTC on 01/11
- 15 sessions — +9.62% · 31/10 candle $88.08 against $80.35 on 16/10
- All-time high — $97.96 · 23/09/2026 · currently 10.1% below
- Supply — 239.4 million circulating · total supply 951.5 million · maximum 1 billion
Price: 31/10 closing candle, Binance HYPEUSDT. Market cap: 31/10 closing price times the circulating supply of 239.4 million (CoinGecko, 18:07 UTC on 01/11, after the cut-off; the supply structure does not change by day); rank by CoinGecko at the same time. 15 sessions: the 31/10 candle against the 16/10 candle. High: CoinGecko's ath field.
Price by Year · Since Launch
- 2024 (from 29/11) — start of year $3.20 · end of year $23.89 · full year +646.7% · low–high $3.20–35.02
- 2025 — start of year $23.89 · end of year $25.43 · full year +6.4% · low–high $9.37–59.39
- 2026 (to 31/10) — start of year $25.43 · latest (31/10) $88.08 · full year +246.3% · low–high $20.53–97.98
Units: dollars. Daily UTC closing candle; low and high are the intraday values. 2024: the change is measured from the 29/11/2024 open, the first day with data; later years are against the previous year-end price. 2026 runs to the end of 31/10, with the 31/10 close from Binance. The daily high according to Yahoo Finance can differ by a few cents from CoinGecko. · Yahoo Finance, HYPE32196-USD
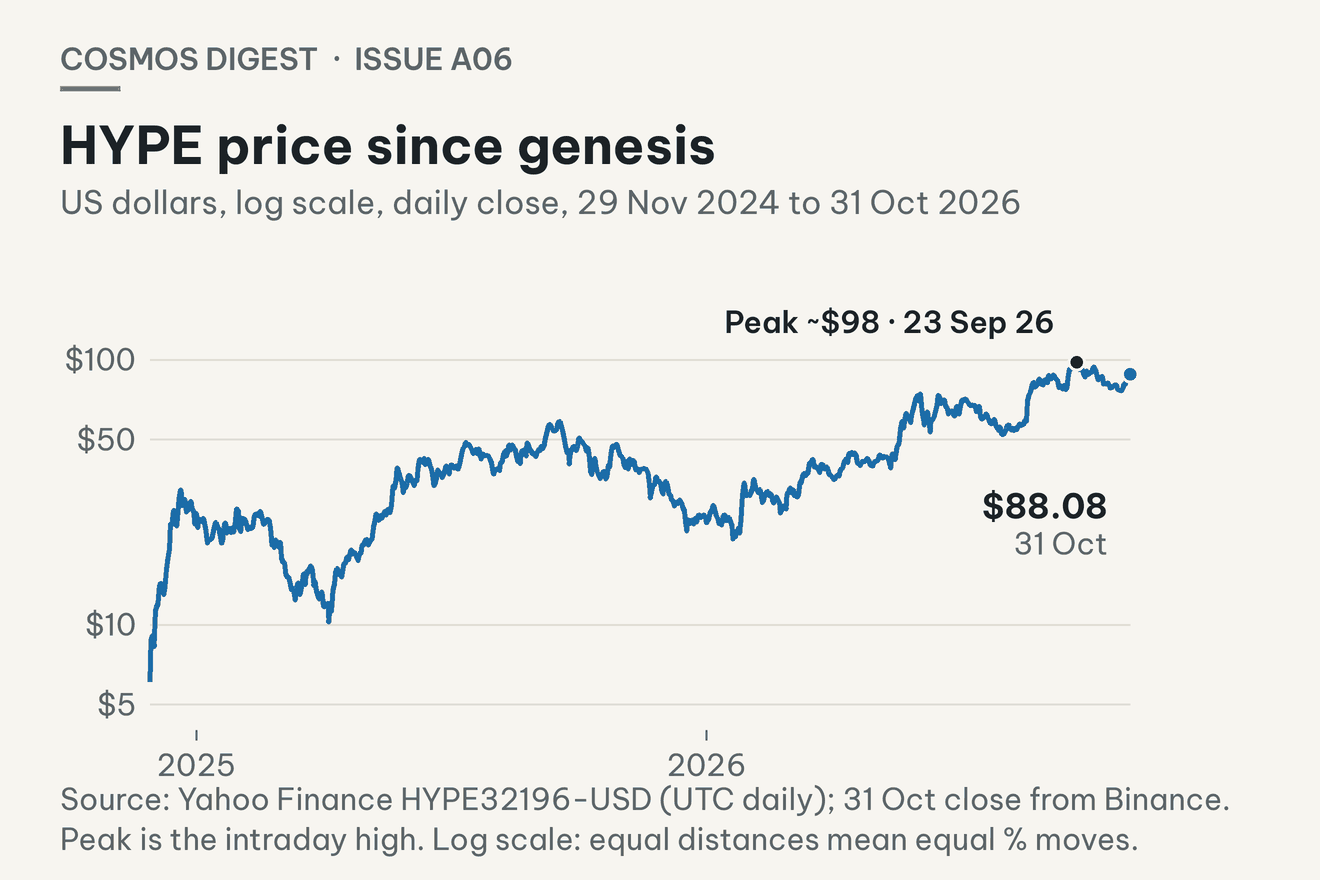
On-Chain · Infrastructure
- Token launch — 29/11/2024, 07:30 UTC
- Validators — 35 registered, 27 active; total stake 440.1 million HYPE; the five largest validators hold 52.7% of the stake (Hyperliquid API, 18:20 UTC on 01/11, after the cut-off; this structure does not change by day)
- Staked supply versus circulating supply — total stake is larger than the circulating supply of 239.4 million because the locked tokens of the core group are also staked
- Trading fees, October — $88.0 million (September: $91.3 million; August: $77.8 million)
- Share to the protocol, October — $69.1 million (September: $74.2 million)
- Cumulative fees — $1.71 billion; on 31/10 alone: $1.47 million in fees
- Block time — 0.07 seconds · 200,000 transactions per second (Hyper Foundation)
Fees and revenue: DefiLlama, to the end of 31/10. Daily perp volume: DefiLlama only opens it to paying accounts, so it is not shown. · DefiLlama, Hyperliquid
Potential · What Is Coming
26/10/2026: Hyperliquid announced its intention to make Payward (Kraken's parent company) the first CFTC-regulated HIP-3 deployer, through Bitnomial, a derivatives exchange and clearing house licensed by the CFTC; HIP-3 is still only on testnet, with no go-live date and no economic terms published. · The Block, 26/10/2026
29/10/2026: ICE, the parent company of the NYSE, agreed with TradeXYZ to bring perp markets built on Hyperliquid to the US under a regulated framework, pending approval: ICE operates the exchange and clearing, TradeXYZ designs the markets, and HIP-3 provides the technology; ICE makes a strategic investment in TradeXYZ. HYPE rose 15% on the day, to around $91.21 at the time of posting. · The Block, 29/10/2026
06/11/2026 and the 6th of each month: the distribution date for the core group's tokens, "if any" (The Block, 29/12/2025). 09/12/2026: the FOMC; not a Hyperliquid matter, but the date that sets risk appetite for every high-leverage token.
Analyst Price Expectations
Among the sources Cosmos Digital could open up to 31/10, no named institutional report gives a valuation method for HYPE. The "price targets" circulating on social media are not cited here.
Four Things to Weigh
One. Unlocking supply. The core group's 238 million HYPE (23.8% of maximum supply) is in a 24-month vesting period from 29/11/2025, on a "non-linear" schedule; circulating supply is now 239.4 million, which means the amount waiting to unlock is equal to everything now circulating. The counterweight is the burn mechanism: total supply is 951.5 million against a maximum of 1 billion; the difference is HYPE burned through the Assistance Fund. Two. Concentrated validation power. 27 active validators, and the five largest hold 52.7% of the stake; a problem at one small group is enough to affect the network. Three. The road into the US is still awaiting approval. Both the ICE–TradeXYZ deal (29/10) and Payward–Bitnomial (26/10) await regulatory approval with no date; and because HIP-3 lets deployers keep up to 50% of fees, the fee flow into the Assistance Fund could shrink in relative terms as HIP-3 grows. Four. A check on this issue's numbers. HYPE +9.62% over 15 sessions (16–31/10) while Bitcoin −4.94% and Ethereum −6.93%: the rise is tied to a news item specific to it (ICE, 29/10), not to the market as a whole; October fees ($88.0 million) were lower than September's ($91.3 million), so revenue did not rise with the price. The Block (12/2025) reported that Hyperliquid's share of on-chain perps had narrowed against Lighter and Aster.
07 — The Story of the Issue
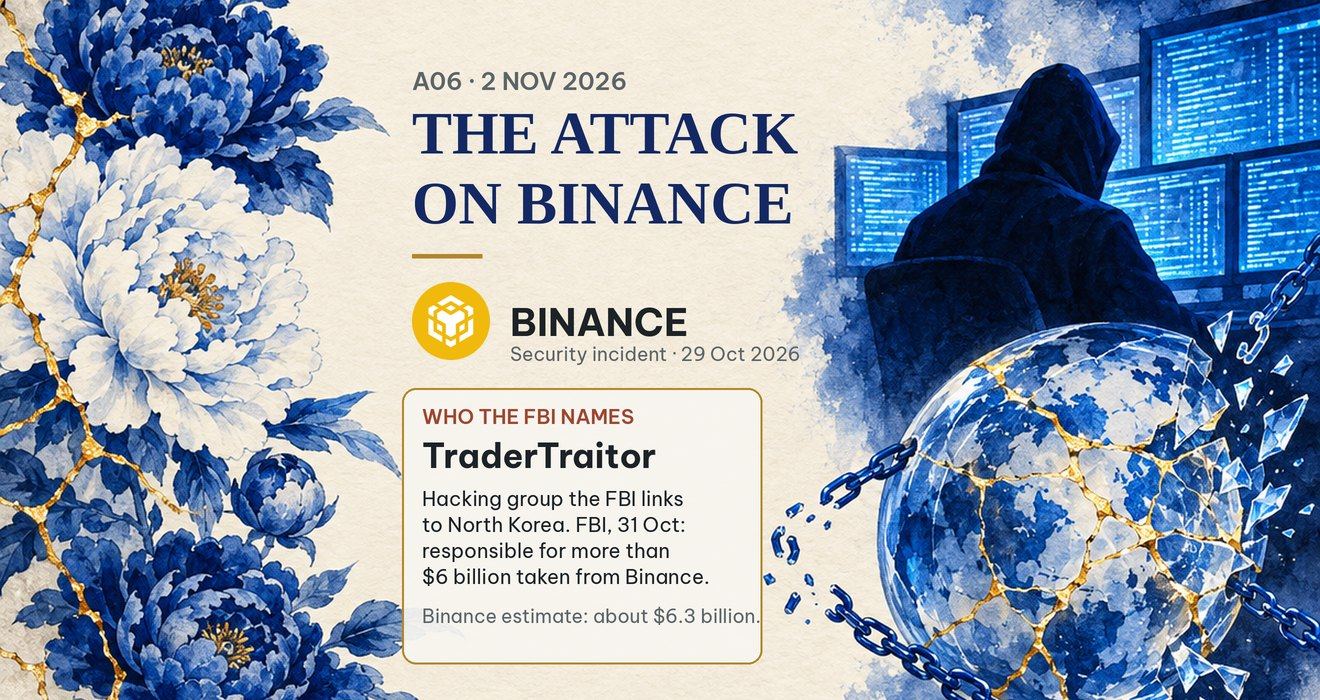
The Largest Hack in History Has Just Been Recorded
On 29/10 (around 20:05 UTC, which is early morning on 30/10 in Vietnam), Binance, the world's largest crypto exchange by volume, had a quantity of assets taken without authorisation that the exchange itself estimates at about $6.3 billion. Two days later the FBI named the culprit. This is an account drawn from the original documents, not speculation.
What Binance Says
The first notice, headed "Security Incident Update", gives total estimated losses of about $6.3 billion, about $3 billion frozen on-chain, withdrawals paused during a security check, deposits not affected, and says Binance "will cover all losses from the SAFU fund and the company's funds". The initial investigation points to the device of an operations engineer as the cause; Binance says there is no evidence that wallet private keys were exposed. · Binance, Security Incident Update
"Security Incident Update #2" gives the start time as around 20:05 UTC on 29/10, still about $6.3 billion in losses and about $3 billion frozen, and says Binance has committed more than $6.34 billion of company capital, covering about 80% of the affected portion and buying the remaining 20% through the market and OTC. Withdrawals will reopen in phases over about 34 hours; initial Proof of Reserves results are expected by Monday 02/11. · Binance, Security Incident Update #2
What the FBI Says
On 31/10 the FBI issued a cyber alert: North Korea is responsible for the theft of more than $6 billion in virtual assets from Binance around 29/10/2026. The FBI calls this activity "TraderTraitor", worked with the USSS and IRS-CI, and observed the attackers converting assets mainly into Ethereum, and expects them to launder the assets further through DeFi and instant-swap services. The FBI urged THORNode operators, RPC nodes, swap platforms and DeFi services to block transactions from the attached address list (hundreds of ETH addresses, 19 BTC addresses, 1 SOL address). · FBI, 31/10/2026
Binance says about $6.3 billion; the FBI says more than $6 billion. The two statements stand on their own, not added together and not turned into a third number.
How Large
The Bybit hack of February 2025, the largest before this, was reported by the press at about $1.4–1.5 billion (Fortune · The Block). On Binance's published figure, this one is more than four times larger. Calling it "the largest in history" here is a comparison with incidents that have been publicly recorded, and rests on Binance's estimate, not an audited number.
Cosmos Digital's On-Chain Check
Cosmos Digital cross-checked independently (on-chain data to 23:20 UTC on 29/10, re-checked on 01/11): the 19 BTC addresses in the FBI's list match a wallet cluster that Cosmos Digital traced on its own from Binance's hot wallet. That cluster received 18,270.20 BTC at 20:20 UTC on 29/10 (block 973732), split into 17 pieces of 1,000 BTC, one of 832.5 and one of 437.7, unspent as of the re-check on 01/11. The five largest ETH addresses in the FBI's list are also the five largest ETH wallets Cosmos Digital traced; as of 01/11 the top three hold 197,460, 137,602 and 78,415 ETH and are still growing, which fits the FBI's statement that the proceeds were converted mainly into ETH. This is Cosmos Digital's own tracing result, not confirmed by Binance or the FBI beyond the match with the published address list.
What Is Not Known
Binance has not published the breakdown of the $6.3 billion by chain and by asset. There is no official figure for the frozen portion by stablecoin issuer such as Tether or Circle. The FBI does not set out its method of attribution. How the market reacted: on 30/10, US Bitcoin ETFs had net outflows of $643.2 million, the largest outflow session of October; Bitcoin's 31/10 candle closed at $77,582; BNB −2.44% over 15 sessions (against Bitcoin −4.94%); the high-yield spread remained 3.26%, with no reaction. Cosmos Digital places this event as a test of scenario K4 (section 05) and will report back in A07 on two facts: whether Binance has reopened withdrawals on all the main networks, and whether the hackers' wallet cluster begins swapping ETH into Bitcoin through THORChain.
— Yin Yang
08 — The Cosmos Ecosystem
CAL Signal issue B10 (01/11): token prices fall, infrastructure bills do not.
CAL's English-language AI technology newsletter took as this week's theme "Models get cheaper. Infrastructure bills do not." In the week of 25–31/10, OpenAI put GPT-6.1 Terra on its API at a standard price 50% lower than GPT-5.6 Terra and GPT-6.1 Sol; in the same week Amazon, Alphabet and Microsoft reported quarterly results: AWS grew 39%, Google Cloud 103% and Azure 48%. Issue B10 also analyses the new terms and the S-1 filing of Anthropic. · Subscribe to CAL Signal
09 — Calendar
Macro · Vietnam Time
- 03/11 — US midterm elections.
- 06/11 · 20:30 — US jobs report for October, 08:30 Eastern time. · BLS
- 10/11 · 20:30 — US CPI for October, 08:30 Eastern time. · BLS
- 13/11 — Eurostat, next estimate of Q3 GDP. · Eurostat
- 25/11 · 20:30 — US Q3 GDP second estimate and personal income and outlays for October (PCE), 08:30 Eastern time; falls after A07. · BEA
Markets
- 02/11 — Binance expects initial Proof of Reserves results, according to update #2. · Binance
- 06/11 — Token distribution date for Hyperliquid's core group, if any (6th of each month). · The Block
- 09/12 — FOMC meeting; the market prices a 73% chance of a 25-basis-point rise (OIS, 31/10). · rateprobability.com
From Cosmos
- 08/11 — CAL Signal issue B11, the English-language AI technology newsletter, a Sunday.
- 16/11 — Cosmos Digest issue A07.
- Next issue — A07, published on 16/11/2026.